

Source: Natalia Filon
What happens when an English war historian with no business background explores the high-stakes world of French luxury goods? You get Kings on the Catwalk — a forgotten gem that unpacks the fierce corporate battle that shaped LVMH, the global powerhouse behind brands like Louis Vuitton, Moët & Chandon, Hennessy and over 70 other brands.
Lately, I’ve been working on two lists;
Companies that have consistently outperformed the market over the past 30 years
Books written about these companies to uncover the mental models, frameworks, and insights that made them exceptional.
One company that stands out on my list is LVMH, the French luxury conglomerate led by Bernard Arnault. As I compiled books on LVMH’s history, Kings on the Catwalk by Hugh Sebag-Montefiore immediately caught my attention. It wasn’t just another corporate biography — it was written by an Englishman with no background in business or finance, whose other works focused on the two world wars. Yet, something about LVMH compelled him to chronicle its formation. That curiosity alone was enough to pique my interest.
Upon reading the book, I realised I had stumbled upon one of the best-untold stories in business history. It dives into the power struggles behind the formation of LVMH, the arrival of Bernard Arnault (often mistaken as the company’s founder), and the internal battles that defined the group’s identity. The book also explores the challenges of mergers, reflects on the nuances of French business culture, and provides timeless lessons for investors and executives looking to build and fund businesses that test time.
Kings on the Catwalk was, however, printed in limited volume, received little publicity, and is now out of stock on major platforms like Amazon (I may or may not have caused this). So, I thought it would be valuable to share the key lessons from this outstanding book with readers who are interested in the luxury industry, business strategy, and investing in companies built for the long haul.
Before diving deeper into the book, let’s set the stage by understanding where the luxury industry stands today — a landscape that looks quite different from the era of LVMH’s formation.
The state of luxury today
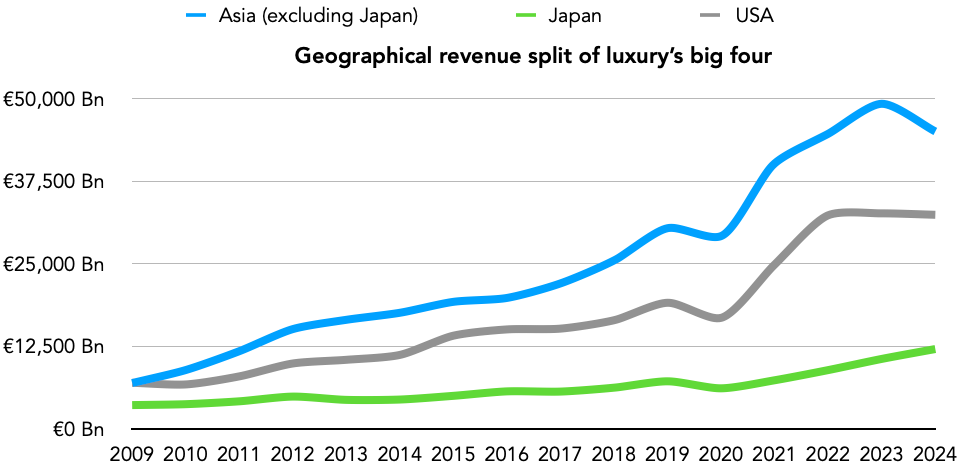
The past two years have been among the most challenging for the luxury industry since the start of the 21st century. The rise of the Asian middle class, particularly in China, had long fuelled demand for luxury goods, creating what initially appeared to be a sustainable growth trajectory for the sector. However, this growth story was disrupted by the Chinese real estate-led downturn. Over the past year, sales in Asia across the "Big Four" luxury companies declined by -8.5%, reflecting a cooling of demand in key Asian markets. In contrast, Japan has reemerged as a bright spot, where a weakened yen, combined with a swift rebound in tourism, has propelled sales growth by 14% for the industry leaders.
Source: Capital IQ
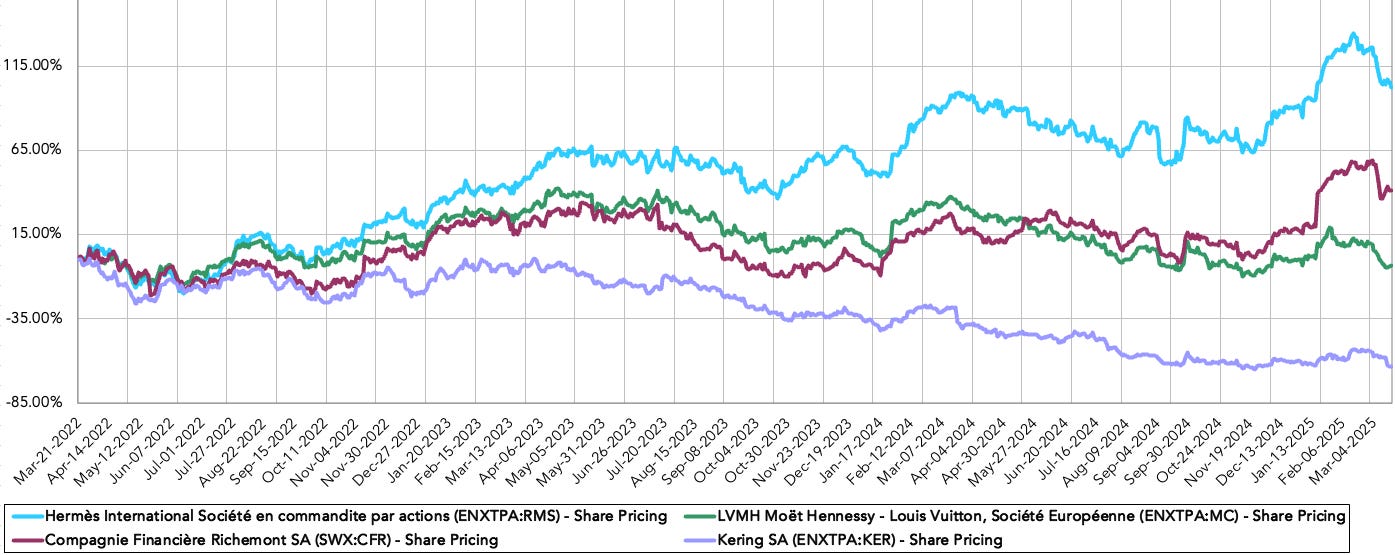
Even the term "Big Four" has become increasingly debatable, with some now referring to a "Big Three," given Kering's recent struggles. The group, which includes LVMH, Hermès, Richemont, and Kering, has seen diverging trajectories, with Kering suffering a series of self-inflicted wounds over the past two years. Missteps at its flagship brand, Gucci, coupled with an underwhelming performance at smaller brands such as Balenciaga, have caused Kering's EBIT to plummet by -46%, compared to a more modest -14.1% decline at LVMH and a 6.8% increase at Hermès in 2024.
The disparity in market capitalisation tells an even starker story. Just five years ago, Kering was twice the size of Richemont and even proposed a merger. Today, however, Richemont is three times larger than Kering.
Source: Capital IQ
With fewer acquisition opportunities on the horizon, luxury giants have increasingly turned inward to cultivate growth through operational excellence and brand quality. No company has exemplified this strategy better than Hermès, which continues to remind investors of the enduring strength of a single-brand focus rooted in heritage, craftsmanship, and culture. Over the past five years, Hermès has delivered outstanding performance, with revenue growing at a 17% CAGR and profits at a 21% CAGR — resulting in 120% and 160% growth, respectively. In today's volatile luxury landscape, it's no surprise that investors have gravitated toward single-brand, multi-product, high-quality companies like Hermès and Brunello Cucinelli, both of which are now valued at 52x their projected 2025 earnings.
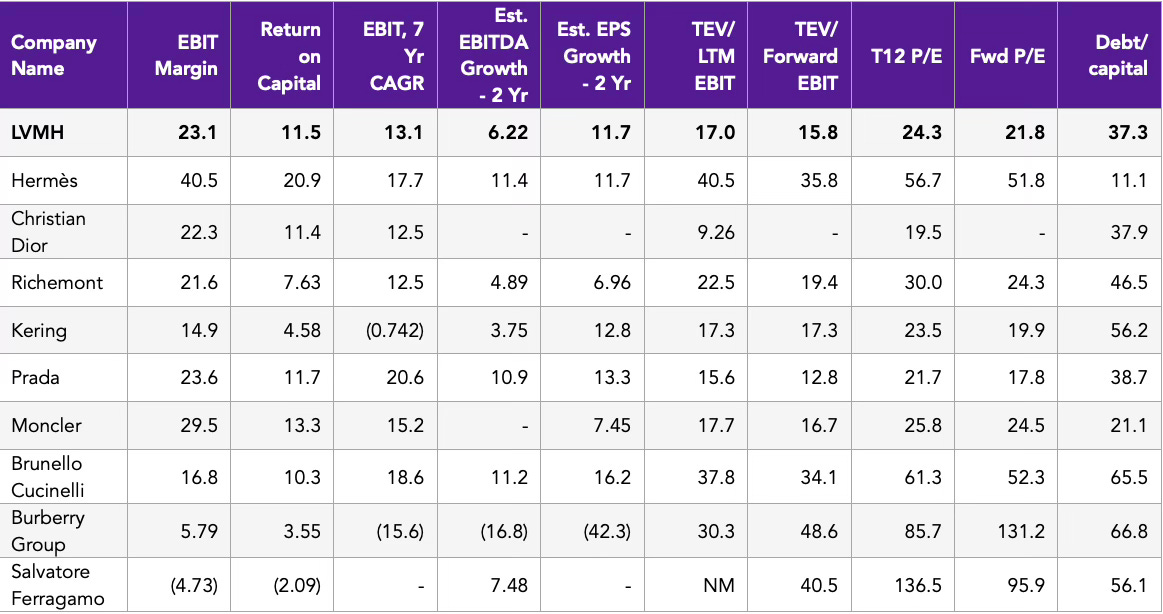
This brings us to the industry bellwether, LVMH, which has demonstrated remarkable resilience despite the shifting macroeconomic landscape, at least far better than its chief rival, Kering. LVMH has balanced timeless appeal with innovation across its brands and products and its most recent acquisition of Tiffany & Co provides a great case study of this LVMH balance. But how did LVMH develop its winning strategy over time in the first place?
To answer that, let's turn back to the book Kings of the Catwalk.
Kings On The Catwalk
The foundations of LVMH were laid by two visionary leaders who applied what would later become known as the "Arnault model" on a smaller scale. However, Bernard Arnault himself cemented LVMH as the world's preeminent diversified luxury conglomerate. To appreciate this journey, I must first introduce the key figures who shaped its early trajectory, as told in Hugh Sebag-Montefiore's book.
Alain Chevalier of Moët & Chandon and Hennessy
The 1980s French business landscape was characterised by two distinct archetypes of entrepreneurs: the traditionalist "old guard" and the forward-thinking "new wave." Alain Chevalier epitomised the former — a class of industrialists whose expertise was rooted more in diplomacy and politics than in capitalism. These individuals were frequently brought in by family-run businesses to provide managerial acumen and leverage their extensive political connections.
Chevalier's journey at Moët & Chandon began when he was recruited by Robert-Jean de Vogüé, the head of the champagne house and a member of the Moët family by marriage. In the early 1970s, Chevalier made a decisive impact by advising de Vogüé to acquire the company's distributors — a strategic move that significantly boosted profitability. Building on this success, Chevalier proposed a merger with Hennessy, a leading cognac producer. His vision proved persuasive, and in 1971, the merger was finalised, giving rise to Moët-Hennessy. Chevalier ascended to the role of general manager and, following the retirement of family members in 1982, became Chairman of the group.
However, Chevalier's tenure at Moët-Hennessy was not without challenges. His aggressive expansion strategy led to costly missteps, including failed acquisitions such as RoC Skincare (acquired in 1978), ill-advised ventures into horticultural businesses in the US and France, and disastrous investments in the cable industry. These decisions resulted in a cumulative loss of Fr 200 million, tarnishing an otherwise stellar track record.
Yet, Chevalier's prowess as a manager was undeniable. He adeptly balanced the competing interests of the Chandon and Hennessy families — a skill that became most evident when Fred Chandon proposed the acquisition of Parfums Christian Dior. Ironically, Chevalier's success with Parfums Dior would later serve as the catalyst for his downfall and attract the interest of Bernard Arnault, who was leading Christian Dior fashion and wanted the Parfums crown jewel back.
Despite these challenges, Chevalier's leadership delivered remarkable financial results. Under his stewardship, Moët-Hennessy's net profits soared from Fr 18 million in 1975 to Fr 827 million by 1986, reflecting an impressive compound annual growth rate (CAGR) of 41%.
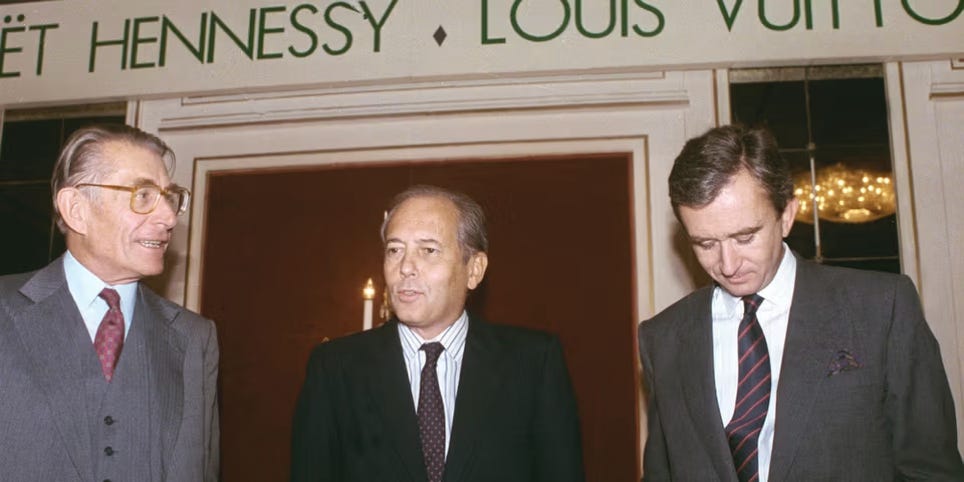
Henry Racamier (left), Alain Chevalier (middle), Bernard Arnault (right)
Henry Racamier of Louis Vuitton and Veuve Clicquot
Positioning Henry Racamier within the spectrum of French business leaders is a more nuanced task. Early in his career, Racamier embodied the archetype of the old-guard industrialist. He founded his steel business, Stinox, in 1946 and grew it into one of France's leading steel manufacturers. Following the 1976 recession, he sold Stinox to the German conglomerate ThyssenKrupp. However, in 1978 — at age 65 — Racamier shifted his focus to his wife's family business, Louis Vuitton. This transition from steel to luxury marked his evolution from a stalwart of the old guard to a visionary member of the new French business elite.
As the head of Louis Vuitton, Racamier fully embraced the high-profile world of luxury. Known for his dynamic lifestyle, he effortlessly navigated between continents — attending glamorous parties in New York on a Monday afternoon, returning to Paris by Tuesday morning for a full day of work with his team. In contrast to Alain Chevalier's more strategic, big-picture leadership style, Racamier was detail-oriented, preferring to personally oversee operations and ensure that his exacting standards were met at every level.
If anyone in the luxury industry grasped the potential of consolidation before Bernard Arnault, it was Henry Racamier. His acquisitions of Veuve Clicquot and Parfums Givenchy laid the foundation for what could have become his luxury empire — had he moved with the same relentless speed and strategic ruthlessness as Arnault. When Racamier assumed leadership of Louis Vuitton in the late 1970s, the company struggled under family control, lagging behind peers like Yves Saint Laurent and Christian Dior. Under his leadership, however, Louis Vuitton's sales surged from Fr 70 million to Fr 4.6 billion by 1989, with EBIT margins approaching 40% — nearly double those of its competitors. A blend of organic growth and strategic acquisitions fueled this remarkable transformation.
From an organic perspective, Racamier demonstrated a profound understanding of Louis Vuitton's heritage and the power of brand storytelling. At a time when Louis Vuitton was primarily known as a luggage brand, Racamier revitalised its image through iconic advertising campaigns featuring misty mountains and serene oceans, evoking a sense of timeless adventure. He also made unconventional yet inspired decisions — sponsoring the America's Cup sailing competition, hosting opulent events for the global elite, and forging partnerships in concerts and operas. His strategic brilliance extended to revitalising franchise agreements with Japanese distributors such as Seibu and Takashimaya, and securing agreements with American retailers like Saks Fifth Avenue and Neiman Marcus, ensuring the brand's global presence. He wanted the profits back from these distributors.
On the acquisitions front, Racamier harboured a vision of creating a powerful luxury conglomerate. In 1986, he acquired Veuve Clicquot, which brought the iconic champagne house under Louis Vuitton's umbrella and included brands like Ponsardin, Canard-Duchêne, and Parfums Givenchy.
Racamier's ambition to transform Louis Vuitton into a dominant luxury powerhouse was well-known. He confided this vision to his Paribas banker, André Battestini, and initiated discussions with Alain Chevalier of Moët-Hennessy about a potential merger. However, Chevalier initially declined the proposal, citing concerns over the cyclicality of the luxury luggage business and the challenge of repeat purchases given the durability of Louis Vuitton products. While Chevalier's concerns were valid, he eventually came to appreciate the benefits of a diversified luxury group and revisited the merger discussions with Racamier a few years later.
Ironically, what was intended to be a mutually beneficial merger between Louis Vuitton and Moët-Hennessy ultimately became the battleground where Bernard Arnault seized control.
Bernard Arnault of Boussac and Christian Dior
Bernard Arnault’s entry into the luxury sector and eventual transformation of LVMH into a global powerhouse was far from an overnight success. His journey in luxury goods began in the early 1980s, a period when financiers and business leaders were beginning to recognise the potential of the luxury industry. Prominent figures such as Edmond de Rothschild and Léon Bresler of Midland Bank had taken stakes in luxury brands like Jacques Fath and Carven, while Financière Truffaut had quietly invested in Kenzo long before Arnault would later bring it under the LVMH umbrella.
But none of these investors matched the vision, ambition, and strategic prowess of Bernard Arnault. At just 35, Arnault took control of Christian Dior by acquiring the debt-ridden textile conglomerate Boussac, a historic company founded by Marcel Boussac and later owned by Financière Agache Willot. The French government had put Boussac up for sale, attracting multiple interested parties, including Alain Chevalier of Moët-Hennessy. However, Chevalier ultimately walked away from the deal, concerned that the mandatory condition of retaining Boussac’s existing workforce could harm Moet-Hennessy’s reputation.
Arnault, on the other hand, was undeterred. He recognised the long-term potential hidden within Boussac’s assets, particularly the iconic Christian Dior brand. In 1984, he acquired Boussac and swiftly took decisive action — terminating over 7,500 textile workers within three years, divesting unprofitable divisions, and focusing entirely on revitalising Christian Dior.
Arnault’s leadership of Dior was a marked departure from that of Jacques Rouët, the larger-than-life figure who had run Christian Dior from 1947 until 1984. Rouët was a bon vivant, well-known in Parisian social circles for his lavish lifestyle and charisma. Arnault, by contrast, was formal, introverted, and intensely analytical — a near-perfectionist who left nothing to chance. Staff at Dior recalled how Arnault meticulously applied cutting-edge MBA techniques to streamline operations and reposition the brand for success.
While Arnault’s analytical rigour was critical, his two greatest strengths were his ability to identify opportunities early and his talent for attracting the right partners to capitalise on them. Nowhere was this more evident than in his partnership with Antoine Bernheim of Lazard, France’s most influential investment bank.
Bernheim was won over by the young Arnault’s vision and agreed to provide the Fr 400 million needed to relaunch Boussac. Beyond the financial backing, Bernheim’s support gave Arnault the credibility and connections to outmanoeuvre the older generation of French entrepreneurs, including Henry Racamier and Alain Chevalier.
This strategic foresight and ability to forge powerful alliances would prove critical as Arnault navigated the complex landscape of the LVMH merger and the ensuing power struggle.
Other important parties
Guinness: Arnault’s unlikely ally
As corporate raiders became more aggressive in the 1980s, Alain Chevalier sought to protect Moët-Hennessy by forging a partnership with Anthony Tennant’s Guinness, the British beverage giant. Guinness had recently acquired Distillers in the UK, a move that gave it control over leading brands such as Gordon’s (the UK’s number-one gin), Tanqueray (the leading imported gin in the US), and a portfolio of whisky brands, including Johnnie Walker.
Chevalier established a joint venture with Guinness to safeguard Moët-Hennessy from hostile takeovers, and initially, the partnership was mutually beneficial. However, the subsequent merger between Louis Vuitton and Moët-Hennessy created unforeseen complications, leading to tensions that ultimately worked in Arnault’s favour.
Arnault leveraged his relationship with Guinness to gain a critical foothold in LVMH, giving him the leverage needed to mount a full takeover of the group.
The French Bankers
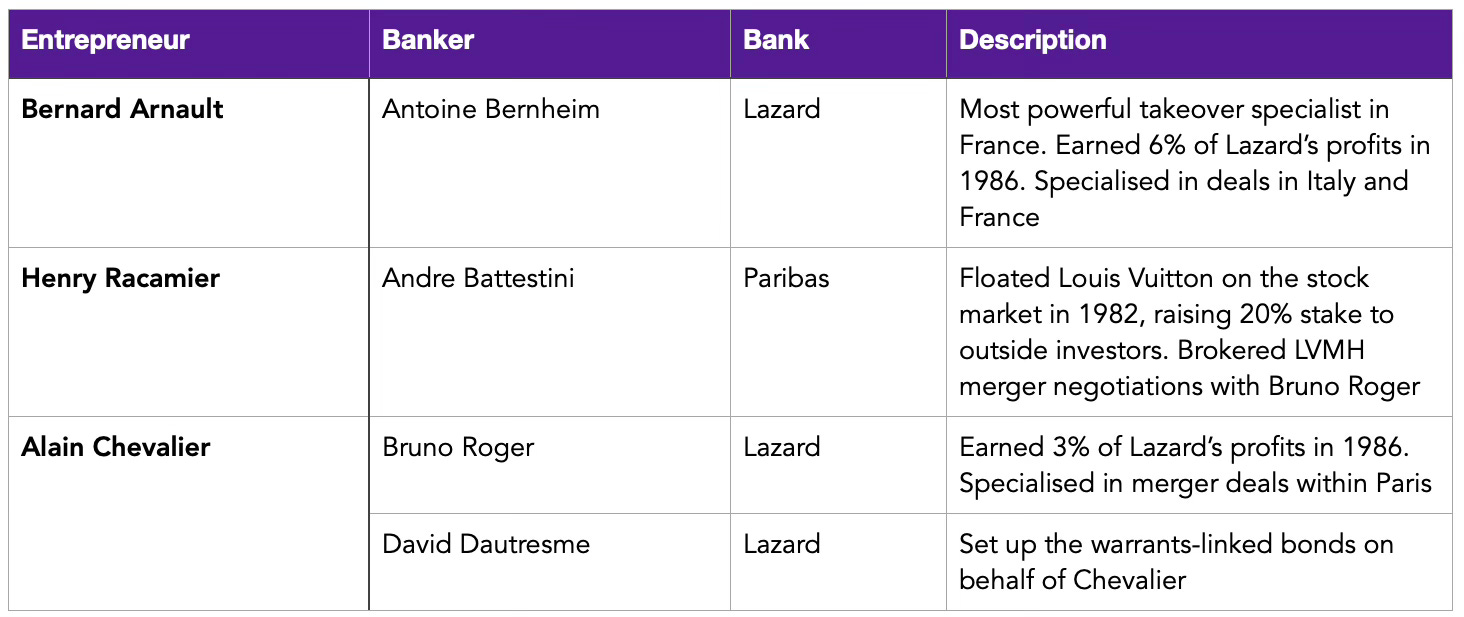
Large-scale mergers like LVMH rarely happen without an army of investment bankers orchestrating the process behind the scenes. Each of the key players involved — Arnault, Racamier, and Chevalier — had powerful financial advisors who provided critical support in financing, structuring, and navigating post-merger complexities.
Antoine Bernheim of Lazard was Arnault’s most trusted ally, playing a pivotal role not just in securing the funds to acquire Boussac but also in guiding Arnault through the intricate power plays that would lead to his ultimate control of LVMH.
Similarly, André Battestini of Paribas supported Henry Racamier in his quest to transform Louis Vuitton into a luxury conglomerate. Interestingly, both Bernheim and Battestini would later go on to join the boards of their respective clients’ companies — a testament to their influence and deep involvement in shaping the future of the luxury industry.
Becoming LVMH
The merger between Louis Vuitton and Moët-Hennessy in June 1987 created LVMH, making it the sixth-largest listed French company with a market capitalisation of Fr 23 billion (on sales of Fr 13 billion) and trading at 17.7x earnings. While the formal merger occurred in June, the groundwork had been laid months earlier. Discussions between Alain Chevalier and Henry Racamier began in April, but their respective banking advisors, André Battestini and Bruno Roger, had already spent countless weeks analysing the deal’s structure and potential synergies.
By the time of the merger, Racamier’s Louis Vuitton was in a stronger position than when he had first approached Moët-Hennessy. The acquisition of Veuve Clicquot had bolstered its portfolio, providing potential distribution synergies with Moët & Chandon. Racamier was also approaching retirement age — in his mid 70s — making the timing appear ideal for a seamless transition.
Or so they thought?
Challenges of the LVMH merger
In mergers of equals, the most significant hurdle is often the alignment of leadership ambitions. History is filled with examples of high-profile mergers that fell apart due to ego clashes — from Quaker Oats and Snapple (1994), Hewlett-Packard and Compaq (2002) to Sprint and Nextel (2005).
Chevalier and Racamier were no strangers to the complexities of mergers. Chevalier had navigated the Moët & Chandon-Hennessy merger, while Racamier had orchestrated the consolidation of Louis Vuitton and Veuve Clicquot. However, the presence of family shareholders in both companies added another layer of complexity, requiring both men to balance the expectations of multiple invested stakeholders.
Even the name of the new entity became a point of contention. Initially, the bankers proposed “Vuitton Moët,” but the Hennessy family felt excluded. To maintain harmony, the name was revised to Moët Hennessy Louis Vuitton (LVMH).
Despite the merger’s success on paper, the differences between Chevalier and Racamier became apparent almost immediately.
Assumptions vs. Reality: Chevalier assumed Racamier would take a step back after the merger, but Racamier had no intention of relinquishing control. He pushed for a clause that would keep Louis Vuitton independent, free from interference by the parent group.
Letterhead Disputes: Racamier insisted on using Louis Vuitton’s signature tinted yellow colour for the company’s letterhead, arguing that LV’s brand commanded more respect than Moët & Chandon. Chevalier conceded, but a week later, the two were embroiled in another dispute — this time over the location of the headquarters.
Office Politics: Chevalier preferred a building near Moët-Hennessy’s offices on Avenue Houche, while Racamier wanted proximity to Louis Vuitton’s Rue La Boétie office. After weeks of negotiation, they compromised on Boulevard de La Tour-Maubourg — but the squabbles didn’t end there. Both CEOs wanted the second floor for their offices, each with their own decor. Chevalier eventually relented and moved to the lower floor.
These disagreements dragged on for months, making it clear that both men couldn't coexist at the helm. One of them would eventually have to step aside to allow LVMH to move forward.
While I could delve deeper into the intricate corporate manoeuvres, power struggles, and courtroom battles that defined the rise of LVMH — and Bernard Arnault's strategic ascent to the top — doing so would not do Kings on the Catwalk justice. The depth and nuance of this story are best appreciated through the lens of the author. I'll leave that exploration for you when you pick up the book. To conclude, I explore five key lessons I learned from the book below.
1. Culture clash
Despite Racamier's point of view, the merger was never one of equals. At that time, Moët & Chandon was still twice as big as Louis Vuitton, which meant power was more likely to lean towards Moët & Chandon. Chevalier had also never truly set what he wanted out prior to the merger agreement, which made managing the culture differences between both players more difficult. This challenge was exploited by Bernard Arnault.
Racamier had invited him to join as a passive shareholder as he needed someone with the financial capacity to maintain Louis Vuitton's independence. Arnault soon realised Racamier actually wanted to break up the whole group and Arnault moved to partner up with Chevalier instead as he saw the benefits of maintaining LVMH.
2. Mistakes from the past
One of the biggest challenges in mergers is that past mistakes and hidden liabilities often follow companies even after the deal is closed — and both Louis Vuitton and Moët-Hennessy were guilty of failing to disclose critical details to one another fully.
Moët-Hennessy's Misstep: Chevalier had entered into a joint venture with Guinness, which included Veuve Clicquot without Racamier's knowledge. This oversight meant that control of Veuve Clicquot's international distribution was handed over to the joint venture, creating unforeseen complications.
Louis Vuitton's Oversight: Meanwhile, Louis Vuitton had an undisclosed agreement with its Southeast Asian distributor, Bluebell Asia, which required the company to pay 11 times its profits if the distribution deal was ever terminated — a costly liability that was not revealed during the merger negotiations.
However, the most damaging oversight involved the warrant-linked bonds issued by Moët-Hennessy. These bonds were designed as a tax-efficient strategy to raise capital at a reduced interest rate of 1% instead of the standard 9.5%, but they came with a hidden cost — they represented 25% of Moët-Hennessy's ownership. Worse still, the deal was brokered by Lazard, which was also Bernard Arnault's bank. This gave Arnault a significant advantage, as he could trace and acquire these bonds, paving the way for his gradual accumulation of a controlling stake in LVMH.
Had both parties been more transparent about these liabilities during the merger, they could have avoided months of legal disputes and eased the integration process while preserving stronger relationships with external partners like Guinness.
3. The luxury cycle
Luxury has always been cyclical — and it always will be. It's easy to believe that soaring sales will last forever during boom periods, but history tells a different story. Understanding these cycles is essential for making informed capital allocation decisions today and in the future.
Take Moët-Hennessy, for example. During the recession of the 1970s, its profits plummeted by -83%, from Fr 218 million to Fr 36 million, pushing the company to the brink of insolvency. This crisis prompted Alain Chevalier to adopt a more diversified, vertically integrated approach that helped stabilise the business. Even at its peak earnings in 1986, Moët-Hennessy's valuation stood at 17x earnings, reflecting the market's understanding that luxury's good times rarely last forever.
Yet today, the markets seem to have forgotten this golden rule. Over the past decade, companies like Pernod Ricard and Brown-Forman have traded at multiples above 30x earnings, suggesting a dangerous disconnect between exuberant investor sentiment and the inevitable cycles of the luxury and beverage industries.
As history reminds us, ignoring the cyclical nature of luxury goods would lead to an expensive lesson for investors.
4. Distribution versus self-ownership
A recurring theme for Louis Vuitton, Christian Dior and Moët-Hennessy was the challenges between the distributor & license and self-operated models. The reliance on license fees was among the first issues Bernard Arnault raised when he arrived at Boussac in 1984, and his goal was to minimise this. Arnault's initial interest in LVMH stemmed from owning the license for Dior's perfume division, which had grown to become almost five times as big as the core Christian Dior fashion brand. In 1987, Dior Parfums had Fr 3.2 billion in sales versus Dior Fashion's 607 million.
Racamier's best decision under Louis Vuitton was renegotiating the contracts with department stores in Japan, such as Seibu and Takashimaya, and then Neiman Marcus and Saks Fifth Avenue in the US. While these retailers could help luxury brands make a quick buck, being able to distribute, manage product placement and messaging, and develop in-store experiences can be massive for increasing brand equity.
Today, brands owned by Kering have had to relearn this lesson on self-ownership over wholesale reliance and have now made a strategic decision to reduce sales from wholesale channels.
“We know that the wholesale channel is apparently quite profitable channel, but we are not afraid to impose to the group some short pain by continuing the rationalisation of wholesale and also to rationalise our distribution more globally speaking” - Jean-Marc Duplaix, Kering’s COO Q2 2024 earnings call
5. Japan and China
If China shaped the luxury industry in the 2010s, then Japan shaped the industry in the 1980s. In the 80s, Japan was nearly 50% of the global luxury industry. Wealthy Japanese consumers had a strong affinity with European luxury brands, and Japanese tourists splurged on luxury goods, which were supported by the economic boom. Entrepreneurs like Racamier and Chevalier capitalised on this boom, and by 1989, Japanese luxury sales for Louis Vuitton were three times the size of its US sales (Fr 2 billion versus Fr 0.5 billion).
Today, China plays the role Japan did in the 80s, and luxury brands have similarly adjusted their portfolio to capitalise on this boom; at peak, China was nearly a third of LVMH's group sales in 2021. The challenge with this strategy is that these brands become sensitive to the slowdown in countries like Japan and China. The best companies to weather this storm are those with vertically integrated business models that can quickly adjust product placements, budgets and people in response to economic changes. How Louis Vuitton and Moët-Hennessy navigated the economic decline seen in Japan during the 1990s serves as a blueprint for luxury brands today with the decline in the real estate-led Chinese economy.
Do you own LVMH?
This was a brilliant and insightful read!! Definitely adding the book to my reading list for the year