

During my weekly Saturday morning checkup on portfolio companies, I came across a Reuters article that mentioned two private equity firms, Thomas Bravo and Hellman & Friedman, are currently looking at FactSet as a take-private acquisition.
At the time of my research into FactSet, while I considered the potential of a takeover given its mid-cap size, the lack of a founder or controlled shareholder, its business quality and current valuation, my investment thesis was solely a long-term buy and hold case.
I’m not a fan of speculative analysis but given Reuters is a very credible source, the article mentioned “three people familiar with the matter”, Thoma Bravo recently raised $34.4 billion for its Fund XVI and Discover Fund V and has already displayed its “deal hunger” with a recent acquisition of WWEX and a $12.3 billion acquisition of the previously listed HCM software company, Dayforce.
Hellman & Friedman, on the other hand, seems less deal active at the moment, but after a successful investment in Allfunds, now in the process of a takeover by a strategic investor, Deutsche Börse, one can also assume they’re also looking at new investments in the sector.
Admittedly, my preference is for these to be simply rumours. A 25% premium from FactSet’s current share price would actually be a failure for us, given the opportunity cost in both capital and time, so as you can imagine, I’d prefer for FactSet to stay public.
That said, there’s little we could do with less than 0.005% ownership of FactSet, so it’s important to consider this possibility, and the rest of the article will assess a potential takeover more broadly from three lenses: management, the potential buyer and current shareholders.
1. FactSet’s management view
FactSet’s management has two options:
Actively seek the best buyer
Strongly refuse to sell
In my view, the key defining factor that should determine FactSet’s management decision should be its confidence in growing net profits and free cash flow above 6-8% annually for the next 4-5 years.
I would suggest that if management is highly confident in its ability to grow FactSet by at least 6-8% over the next few years, primarily through subscription growth, staying public would be more accretive to both management and shareholders.
However, if management has low confidence in its ability to deliver net profit growth by at least 6% in the medium term, selling FactSet now is the better decision (I hope this isn’t the case).
FactSet’s issue today isn’t profitability; it is earnings growth and resilience, and proving its strength here, in my view, is the single most important factor between a 13x P/E and 21-23x P/E valuation by the market.
2. The Private equity’s view
I’m not surprised by the interest from private equity firms:
FactSet retains 90% of its clients annually, with 95% retention for its annual subscription value.
It is mission-critical to its customers.
It’s highly profitable, cash generative and maintains a good balance sheet with further leverage potential, as is typical with PE.
Private equity is a major client of FactSet, and as owners, they would likely share creative operational ideas on how best to deliver earnings resilience. I suspect Preqin and BlackRock are an ongoing case study of this with the recent BlackRock Aladdin integration.
The purchase price is low compared to alternatives. At a 25% premium to today’s market cap, FactSet would be valued at. For perspective, although a totally different business model and financial profile, Thoma Bravo’s listed SailPoint is currently valued at 27x its 2028 market estimated EV/EBITDA.
Given evidence of both private equity and financial exchanges’ long-term interest in financial market data companies, should a PE owner prove successful during a 6 to 8 year ownership period, there would be a few exit options available, including a re-IPO, with IHS Markit serving as a good case study.
Finally, Thomas Bravo’s portfolio company, BlueMatrix, recently acquired RMS Partners from FactSet, and one can assume there’s already a relationship between both companies from this deal. Achim Fehrenbacher, a former 20-year FactSet veteran now works with Thoma Bravo’s BlueMatrix, and I suspect Scott Crabill, a Thoma Bravo managing partner, would be leading any deal with FactSet. After assessing Thoma Bravo’s 17 current Application Flagship investments, I don’t see any other similar financial market data investments and given their track record of merging similar companies, this could be a downside to any take-private transactions.
Looking more broadly at the listed U.S. financial information services space, the PE firms currently have 3 take-private potential targets:
Morningstar: Among the three companies, Morningstar has the most resilient business model given its diversified products and client base, growth potential, and its balance sheet is currently PE-friendly. The challenge they’ll face is the founder and chairman, Joe Mansueto, a 45% owner of Morningstar. Having watched some of his interviews and read some shareholder letters from its CEO, I doubt he’s likely to sell. A PE buyer would also have to purchase Morningstar at a more premium multiple and at a higher enterprise value (>$10 billion).
Gartner: Compared to the other two companies, Gartner’s services are most likely the least sticky (85% client retention rate), have the slowest organic growth potential, the most leveraged, and also most at risk to the ongoing AI challenges. Like FactSet, though, Gartner isn’t founder-owned, with its long-time CEO, Eugene Hall, owning roughly 1.7% of its shares, which eases a deal process.
FactSet: FactSet isn’t as high quality and diversified as Morningstar and potentially faces more AI threats with a slower growth potential, has limited room for margin expansion but that said, its lower purchase price and more simplified acquisition process likely make it the most attractive of all three companies from a PE perspective.
As a result of this, I think the possibility of interest from private equity firms is quite real, and if I were to speculate on reasons why it was leaked to Reuters, the most interested buyer (I suspect this is Thoma Bravo) is probably looking for another PE firm to partner with for the deal, given the enterprise value.
Given that Thoma Bravo is also the largest software PE firm and several rivals like Apollo and Blackstone have taken a stance against software companies, I suspect there’s limited competition in a FactSet acquisition.
Of course, these are just my thoughts; I have no insider insights here.
3. The shareholder’s view
FactSet has a very passive shareholder base, with the majority of its shares held by big American passive institutional funds. BlackRock, Vanguard and State Street, the three largest passive firms, hold a combined 25% of FactSet’s shares. Among the top 20 shareholders, I suspect only Baron Capital, a 10.2% shareholder, led by one of the all-time investment greats, Ron Baron, is active.
Altogether, the top 20 shareholders were net buyers (2.6 million shares or 7% of shares outstanding) of FactSet’s shares during Q4 2025 from the latest 13F filings.
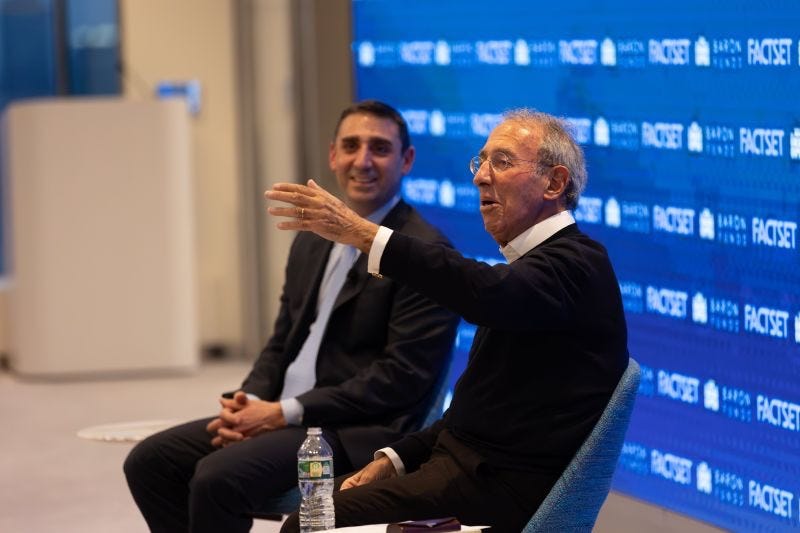
In late December 2025, Ron Baron spoke quite highly of FactSet and its new CEO during a CNBC interview, and in the last five months, Baron Capital have increased its position by 108%, the first substantial increase since Q1 2008, having held its shares for more than 20 years. This is also the first time they’ve ever held more than 10% of FactSet’s shares.
As you can imagine, Baron Capital would likely have a key say on if FactSet gets sold (they also own shares in the other two options, Morningstar and Gartner), and given the history and profits gained over the decades investing in FactSet, if I would guesstimate, I suspect they would probably push for a 40% premium to today’s price, $297 per share or a $11 billion market cap exit.
Final thoughts
While I’d prefer for FactSet to stay public, after weighing up the broader competitive landscape, the stated PE interest and some speculative thoughts, I suspect FactSet might not be a publicly listed company by the end of the year.
For now, I’m staying put, though. I maintain the full FactSet investment position and continue to monitor developments in the broader AI landscape, its peers and of course, FactSet’s earnings results (Q2 2026 FY), next scheduled for 31st March 2026.
As a long-term investor, I do hope this is all speculation, but I will double down on researching new ideas in case of a take-private offer.
Thanks to Dede Eyesan for highlighting FactSet Research Systems Inc. (FDS; FDS US).
FDS' short interest has increased to 10%. Seems like there are hedge funds that are betting against a take-over.
I wonder whether you have any insights into this?
If the rumours turn out to be factual, it follows that Jenga is among investors with a keen eye for realiseable/ locked-in value of FactSet.
Hopefully, the shareholders should be able to hold out for much more than a 25% premium. We can be hopeful !