

Source: Jim Lambert, Denver International Airport
Confession Time. Growing up, I was often among the tallest in my class, but I also had an unusual fear—heights. This condition, known as acrophobia, was most apparent when I was flying. My coping mechanism? Simple: sleep through the whole flight and wake up just before landing.
However, the demands of investing—travelling for company visits and hosting roadshows—pushed me to confront my fear. Whether I liked it or not, I needed to fly to leave the UK for work. That meant enduring long hours in check-in and boarding queues (hello, Lagos Airport), and if I wanted a hot meal, I was forced to pay premium prices at airport restaurants.
These experiences got me thinking. Despite their inconveniences, airports are indispensable to our lives—whether we love to travel or dread it. They are crucial, enduring businesses that serve a universal need. Even for those who would rather skip the whole flying thing, airports remain a vital part of the infrastructure.
Interestingly, while airlines come and go, airports possess staying power. Of the largest 50 US airports, the average age is 80 years. Last year, airports facilitated nearly 60 million tonnes of air cargo and over 4 billion passengers. Yet, despite their pivotal role in the global economy, their investment coverage is surprisingly smaller than expected. In fact, up until the 2000s, fewer than ten airport companies were listed globally. Fast forward to today, and the picture has slightly changed. There are 24 listed airports worldwide, primarily concentrated in Latin America, Europe, and Asia—none in the U.S.
In this deep dive, I will explore the history, economics and attributes of listed airports and share a deeper dive into two Mexican airports I believe are of high quality, undervalued, with some growth potential: Grupo Aeroportuario del Centro Norte (OMA) and Grupo Aeroportuario del Sureste (ASUR).
Here’s what you can expect in the two-part report:
Value creation: The role airports play in society, some history of airports, their barriers to entry, and tourism’s impact on airports’ growth potential.
Industry drivers: Delving into key regulatory factors, the airport-supply chain relationships, recent privatisation efforts and an overview of Mexican airports. I also examine my 12 investable listed airports from a quality perspective and compare how airports perform relative to other transportation sub-segments.
Unit economics: In the second part, I’ll dive into the unit economics of Mexican airports, comparing them to industry leaders. This includes an exploration of concession terms, non-aeronautical revenue, diversification efforts, and cost structures.
Competitive advantages: An in-depth analysis of OMA and ASUR’s competitive advantages relative to other airport groups, focusing on their quality scores and weaknesses within their business models and regulatory landscapes
Valuation: My assumptions and potential internal rate of return (IRR) for both OMA and ASUR
Concluding thoughts: Alternative airport stocks to consider, along with some insights on Mexican stocks beyond the airport sector
1. Value creation
What would happen if airports ceased to exist?
Last week, London got a taste of this question as a fire outbreak at a nearby electrical substation brought Heathrow airport to a standstill, disrupting over 200,000 passengers and 1,300 flights with an estimated economic loss in the hundreds of millions of pounds. The disruption reminded governments, travellers, and the broader economy of how vital airports are to society, supporting the flow of people and goods. Yet, despite this central role, airports as an investment theme remain broadly understudied, under-followed and undervalued.
The twelve listed airports I will introduce you to in this first half of the airport's deep dive are valued at an average of 16x earnings despite having an average return of capital of 11%, operating profit margin of 38% and a forward earnings growth estimate of 10%. In simpler terms, these airports are valued at lower multiples than the market despite earning a better return on capital and growing earnings faster than the average listed company.
I don't believe this valuation gap is justified and we aren't alone with this view. The world's largest private equity infrastructure fund, Global Infrastructure Partners, recently announced the acquisition of Malaysia Airports Holdings, while Denmark's Finance Ministry announced at the end of 2024 its decision to extend its investments to a 98% stake in Copenhagen Airports (Københavns Lufthavne). Just last week, Blackstone’s Infrastructure Fund agreed to a 22% stake in the owner of Aberdeen, Glasgow and Southampton's airports, AGS. It's clear private owners are taking advantage of the valuation gap, but this market sentiment for airports hasn't always been the case. The 2000s was a golden decade for airport stocks, but before we discuss the privatisation of airports, let's first look into the history of airports as an infrastructure.
A brief history on airports
Airports are inherently tied to the development of aviation. Building on George Cayley’s 1799 study of a modern plane, the Wright brothers achieved the first controlled and sustained flight of an aircraft in 1903 and two years later, launched the Wright Flyer III. The breakthrough spurred the demand for pilot training and in 1909, the Wright brothers founded the College Park Airport in Maryland, USA—the world's oldest continuously operating airport.
In Europe, Hamburg Airport opened in 1911 as a small airfield in Germany, playing a key role in shaping the region's aviation infrastructure. In Asia, China was proactive in anticipating the rise of aviation, opening Beijing Nanyuan Airport in 1910 and establishing a flying academy three years later.
What truly propelled the developments in airports was the First World War. Governments around the world made it a strategic mission to invest in aircraft technology, construct runways and expand airfield infrastructure like hangars and control towers. After the war, commercial flights began growing, with the first international flight taking place between the US and Canada in 1919. Closer to home in the UK, Croydon Airport opened in 1920 and became the first airport in the world to introduce air traffic control, setting the stage for safer air travel.
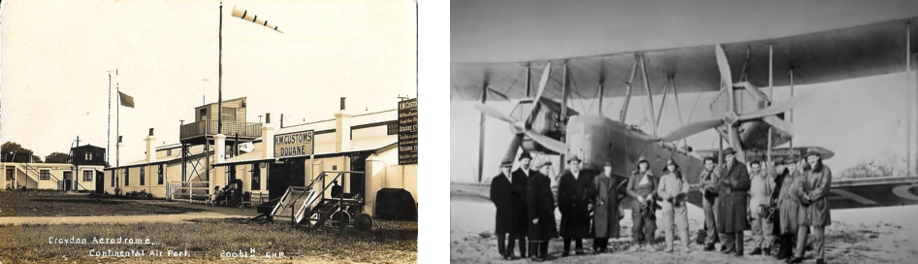
Source: historiccroydonairport.org.uk
The next big leap for airports came after the Second World War and marked the beginning of the "Jet Age", with a significant increase in commercial air travel. Aeroplanes became more technical, larger and more efficient; Boeing developed the 707 for commercial flight (1957), and regulatory bodies like the Federal Aviation Administration (FAA) were established to standardise and regulate airport operations. Governments poured more investments into major international airport infrastructure. As the world's economies became more interconnected, demand for air travel surged, driven by tourism and international business.
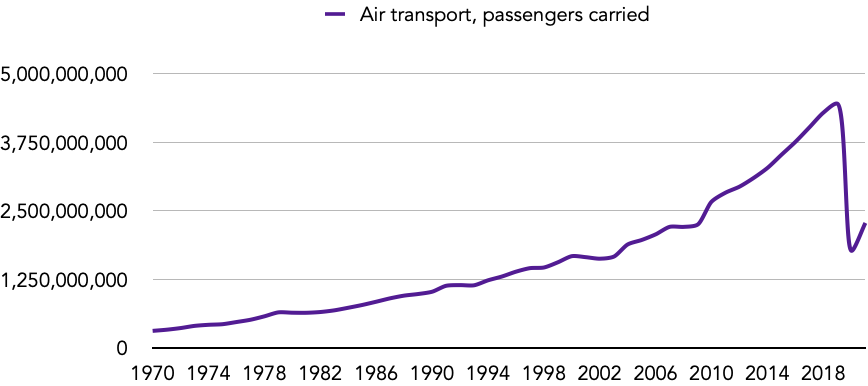
Source: World Bank
Today, there are more than 40,000 airports globally, with approximately 9,000 serving commercial flights and generating over $230 billion in annual revenue. The value creation of airports can be summed up in two key areas: global trade & connectivity and tourism & hospitality.
Global trade and connectivity
There is no globalisation without airports. Alongside airlines, they serve as the backbone of international trade and the movement of goods and people. While air freight represents just 1% of total trade tonnage, it accounts for 35% of the total value of internationally transported goods. This is because air freight is primarily used for high-value, time-sensitive products such as electronics, luxury goods, art, and medical supplies.
Airports play a crucial role in facilitating this trade, providing dedicated cargo terminals, warehouses, and specialised storage facilities. Many are seamlessly integrated with road, rail, and sea transport networks, ensuring smooth supply chain operations. As global trade grows and supply chains evolve, airports remain indispensable logistics hubs.
Tourism and hospitality
Beyond trade, airports serve as gateways to the global travel economy, supporting a key downstream sector: tourism. According to IATA, 4.7 billion people travelled by air in 2024, 40% being international flights. Airports are critical enablers of this sector, helping to drive the steady rise in tourist flows, holiday packages, and international travel experiences.
As the first point of contact in many destination countries, an airport can shape the overall tourist experience. Research from the University of Mauritius highlighted that airport service quality significantly influences overall tourism satisfaction and a traveller's likelihood to revisit a destination. This underscores how airports contribute not just to travel but to the success of local tourism industries.
Beyond aeronautical services, airports generate substantial non-aeronautical revenue, further supporting tourism-related activities - hotels, duty-free shopping, entertainment venues, and major international events all benefit from airport infrastructure. Since the establishment of the world's first duty-free shop in 1947 at Shannon Airport, Ireland, the duty-free industry has grown into a $47 billion market, becoming a critical part of global consumer retail.
Today, hundreds of airports worldwide are operated as private companies—either independently or as part of airport groups. Many are owned outright, while others operate through concession agreements. However, this commercialised approach to airport ownership is a relatively recent development.
2. Industry overview
Ten years of global privatisation
The 1995 - 2005 ten-year period saw a wave of airport privatisations and concession tenders around the world. Countries globally looked to the successful IPO of the British Airports Authority in 1987, which raised £1.2 billion, marking the first airport privatisation as an example of how public sector assets could be offered to private investors. In Europe, Austria followed the UK with the privatisation of Flughafen Wien (Vienna Airport) and then Italy with the partial privatisation of Aeroporti di Roma in 1997.
In Asia, China, India and South East Asian countries were active in the privatisation trend but to varying degrees of private ownership and agreements. China listed some airports in the late 1990s, like Shanghai International Airport, but private and international investors had limited access to owning their shares. Malaysia and Thailand were early Asian players in airport privatisation and also served as great case studies of successful airport privatisation in emerging markets.
Privatisation has enhanced airport profitability and efficiency, pushing operators to adopt long-term strategic planning while diversifying revenue streams beyond aeronautical fees. It has reduced financial and operational burdens for governments, setting a blueprint for Public-Private Partnerships (PPPs). For instance, ahead of the privatisation of Ninoy Aquino International Airport, Philippine government officials emphasised that transitioning to private ownership was the most effective way to improve earnings, eliminate inefficiencies, and reduce delays—a sentiment echoed across various markets.
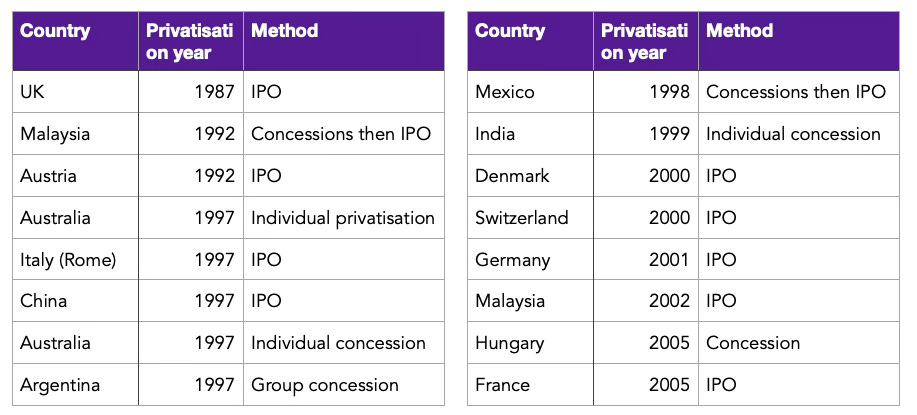
Absence of US participation
In the table above, you may have noticed a missing global player in the airport privatisation trend: the US. Despite several attempts, such as Chicago's bid to privatise the Midway Airport, the US has largely resisted airport privatisation and is unlikely to in the future for a few reasons. First, public sector airports in the U.S. can raise tax-exempt revenue bonds and second, they receive substantial federal Airport Improvement Program (AIP) grants if they commit to not making profits from airport operations. The only successful privatisation in the US is San Juan, Puerto Rico, which is owned by one of the Mexican airport groups I will discuss in the investment cases section.
Today, it’s estimated that nearly 20% of all airports globally have some form of private participation (50% in Europe). Still, despite the privatisation status, airport owners don't have free will to set their economics and capital expenditures and are typically under strict regulatory oversight to ensure their policies, rates, and budgets are fair for all stakeholders.
Regulatory perspective on airports
There are two ways to divide airport operations. Aeronautical versus non-aeronautical revenue or regulatory versus non-regulatory activities. Like any mission critical infrastructure, airports are under strict regulatory frameworks to ensure they serve the population and relevant stakeholders while achieving targeted financial obligations. These frameworks dictate pricing (e.g., landing fees, passenger charges), operational expenditures (e.g., terminal maintenance, security), and concession agreements with government bodies.
At the global level, the International Civil Aviation Organisation (ICAO), the International Air Transport Association (IATA), and, to some extent, the US Federal Aviation Administration (FAA) are the central regulatory bodies. While these institutions ensure standardisation and safety, national regulators directly influence airport operations and investment risk. National authorities approve airport budgets, oversee compliance with international standards, and set concession terms. Below, I outline the regulatory bodies governing key listed airports in our deep dive.
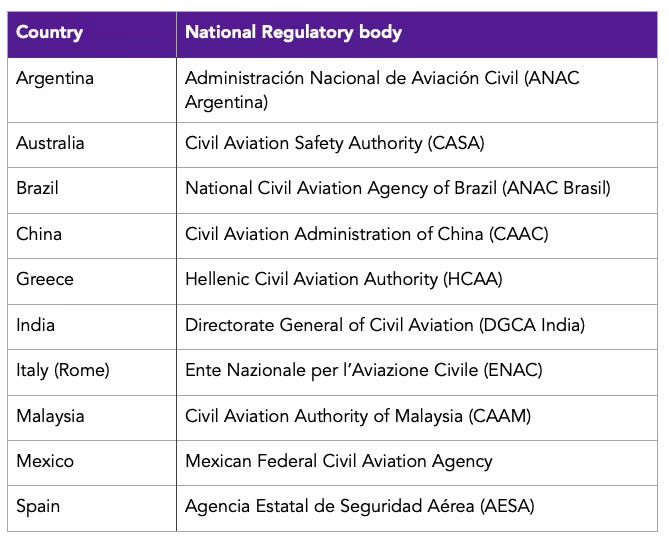
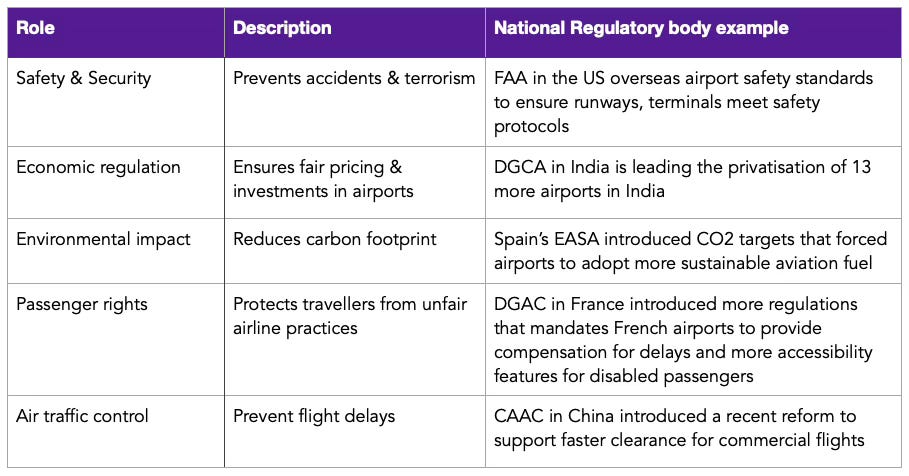
Regulatory risk
The single most critical risk for airport investors is the regulatory risk, as changes in regulatory approach (and government) quickly impact the economics and fundamentals of airports. Abrupt shifts in policy can cause sharp swings in investor sentiment, leaving permanent damages to their investment cases. In late 2023, the AMLO government in Mexico abruptly announced an increase in concession fees, leading to Mexican airport stocks falling by -25% in a single day.
A more extreme risk is concession revocation—where regulators terminate an airport operator's contract, wiping out years of capital investment and future earnings. While rare, it has occurred - Corporación America Airport, a Latin American-based group, saw its Natal Aluízio Alves International Airport in Brazil terminated.
For investors, it's essential to adjust for this risk in valuations; for example, I automatically assign airport groups with concession models with a lower multiple and avoid investing in airports where most concessions expire within 10 years. Additionally, many regulatory bodies set a point-based termination system where concession terminations are dependent on whether airport operators fail to meet or violate operational or financial KPIs and terms. Most national bodies publish these lists annually so one can quickly see which are more likely to be sanctioned or have a higher probability of the concession termination risk.
Breakdown of listed airports
There are 24 listed airport groups, and in the table below, I segment these into five geographical regions, with China hosting six companies, five in Europe (North and West), Europe (South) and the Rest of Asia (including Australia) each and four in Latin America.
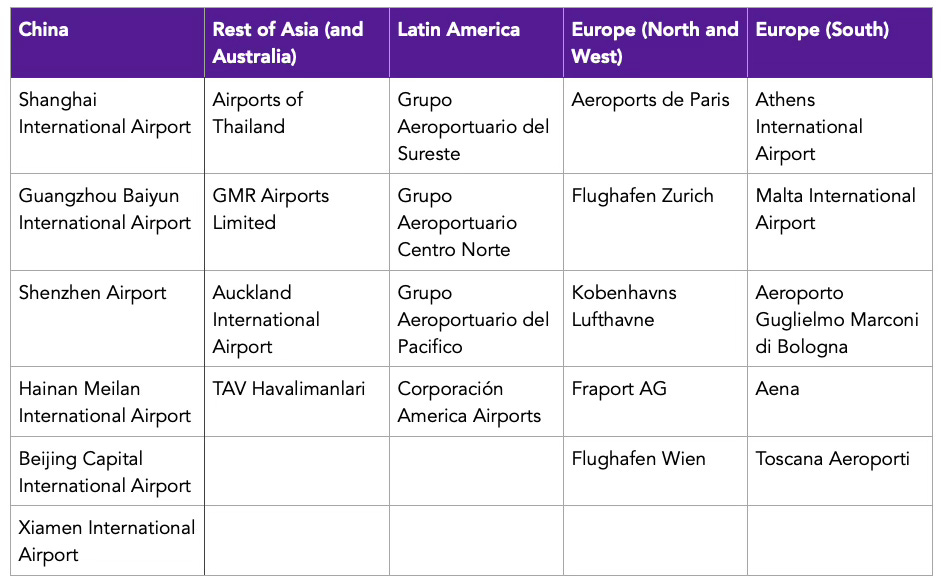
China: The six Chinese listed airport groups are state-owned enterprises that went public during the 1995–2005 privatisation wave. Collectively, these companies have returned just 4.97% per year (including dividends) over the past 20 years. Their underperformance can be attributed to two main factors: overvaluation and capital efficiency. In the mid-2000s, there was excessive optimism about Chinese infrastructure growth prospects, leading these airports to trade at price-to-earnings ratios of 40–45x, which did not align with their earnings growth rates.
Additionally, Chinese airports have faced high capital expenditures, reducing shareholder returns. For example, Shanghai International Airport has spent CNY 30 billion in Capex over the past 20 years while generating a net profit of only CNY 29 billion in the same period. Among these, Xiamen International Airport stands out as one of the better-capitalised and more promising Chinese airport.
Rest of Asia (and Australia): The rest of Asia was broadly slower than China with listings but is represented across the listed airport space with varying models. Airport of Thailand owns and manages the six major airports in Thailand and, in my view, is among the higher quality tier 1 airport stocks due to its market positioning with Thailand's tourism economy and domestic market share potential as a percentage of all flights in Thailand. TAV Airports has a more "multi-concession" model similar to Corporación America Airports due to its range of airport concessions beyond its core country, Turkey - Kazakhstan, Tunisia, Georgia and Armenia.
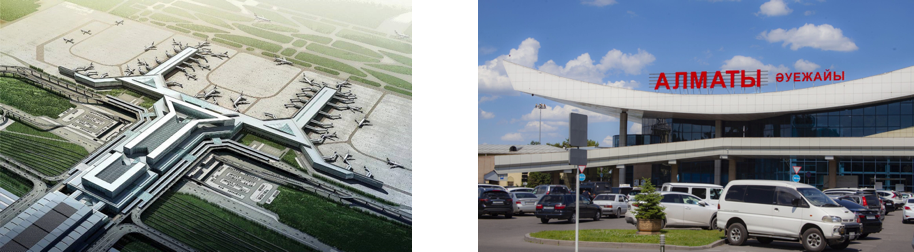
Shanghai Airport (left) and Almaty Airport - TAV Airports (right)
Latin America: Latin America hosts four airport groups collectively managing 90 airports led by Corporación América Airports with 52 airports in Brazil, Argentina, Italy, Uruguay and other locations. Unlike their Chinese counterparts, these airport groups are pure private businesses that own concessions to operate various airports and have also established their operational track record since the late 1990s, when Mexico began privatising airports. They have also benefited from South America and the Caribbean's booming tourism industry, driving profitable growth in international travel fees. Notably, two of this report's investment cases—OMA and ASUR—belong to this segment.
Europe (North and West): European airports are divided into two categories based on ownership models and strategic approaches. The Northern and Western European airport groups typically own airports outright, often with their respective governments holding majority stakes. For instance, Denmark's government owns 98.6% of Københavns Lufthavne. These airports also invest globally, e.g., Aéroports de Paris holds significant stakes in TAV Airports (Turkey, 46% stake) and GMR Airports (India, 30% stake).
Others, like Københavns Lufthavne, have made profitable investments in Mexican and Chinese airports. Due to their stable ownership structures and lower regulatory risks, these airports generally trade at higher valuations (>20x earnings).
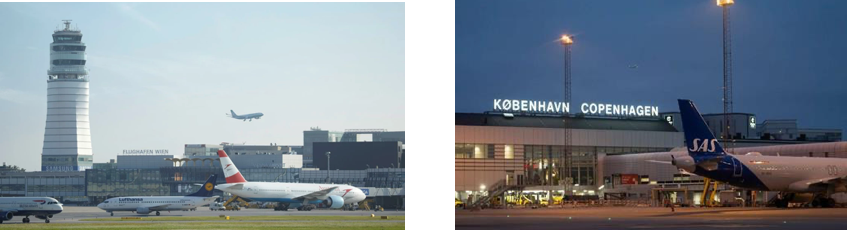
Flughafen Wien (left) and København airport (right)
Europe (South): Apart from Aena, the world's largest airport group by passenger volume, the rest of Southern Europe's airport groups are more emerging players in the airport space with more recent group formations; Athens International Airport only went public last year. Given the nature of their domestic economies they are also more exposed than their northern counterparts to the tourist economy. They maintain a concession model with their governments, making them more uncertain and riskier due to regulatory risks. Due to their smaller size (the Italian and Maltese airports have a market cap of less than $1 billion), they are more underfollowed and broadly trade at lower valuations.
Jenga IP’s 12 Investable listed airports
After reviewing each listed airport, I split them into two halves, with one half representing the twelve airports I view as most investable based on quality, growth, and valuation metrics and the second half being companies I view as less investable today. Some airports may be solid businesses but challenging for foreign investors due to shareholding restrictions (e.g., Chinese airport stocks) or low float availability (e.g., Copenhagen Airport, with only 2% free float).
In the table below, I share these twelve investable airports and include some key facts such as countries where their airports are located, the number of airports, revenue, concession length and nature and their annual passenger count and the Jenga Quality score I assigned.
For new readers, I explained what the Jenga Quality Index means and why it’s an important tool in my analysis in last month’s Alphabet deep dive here. For a recap, the quality score is a scoring system out of 100 points based on ten factors I believe determine a company's quality;
New entry difficulty
Nature of demand
Balance sheet strength
Profit margin
Market & positioning
Pricing power
Value chain control
Value created to society
Culture
Test of time
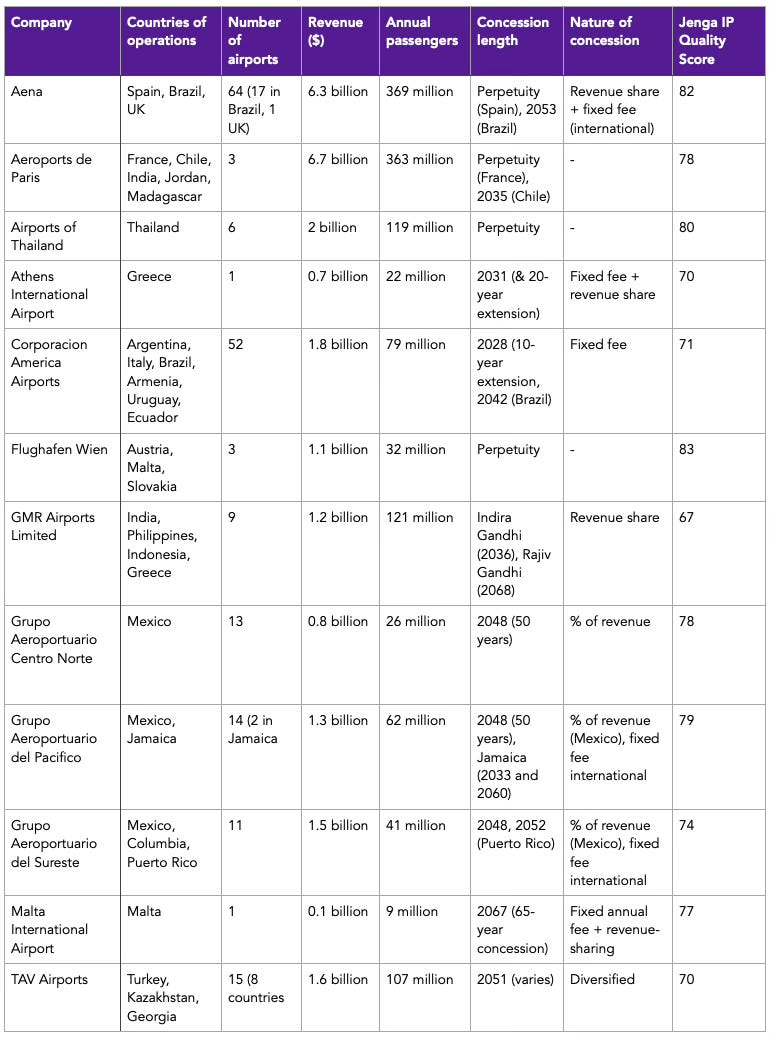
From the table above, a few things particularly stand out;
Globalised: Airports are more global than one might think. The more mature and larger airports took advantage of their scale and first-mover advantage in airport privatisation and invested in several other smaller and emerging airports. The two largest airport groups, Aena and Aéroports de Paris (ADP), have invested beyond their home countries (ADP with GMR in India and TAV Airports in Turkey) and own concessions in other countries and continents (Aena with Luton Airport in the UK and 17 Brazilian airports). The international standardisation for airport management has made it easier for these groups to operate internationally and globally, and I expect this trend to persist for many years.
Domestic monopolies: Alongside railroads, financial exchanges and to some extent, utilities, airports are one of the very few businesses that have the permission to become domestic monopolies. Half of the twelve companies above can be considered as domestic monopolies where they own a majority share of airports from a flight market share - Malta International Airport has a 100% market share in Malta, and Airports of Thailand has an 87% market share in Thailand. However, government ownership is often a feature in these monopolies, which can presents pros and cons for investors. While state-backed ownership can provide stability, it can also lead to regulatory interventions that may impact shareholder returns.
Concession variability: When the airport group doesn't own the physical airport outright, airports employ a concession model with the government. These concessions vary in length, fee payments, and overall terms from the examples above. The Mexican airport's concessions last for 50 years, with the operators paying 9% of their revenue to the government, while CAA in Argentina's concession durations are shorter and are more fixed fees.
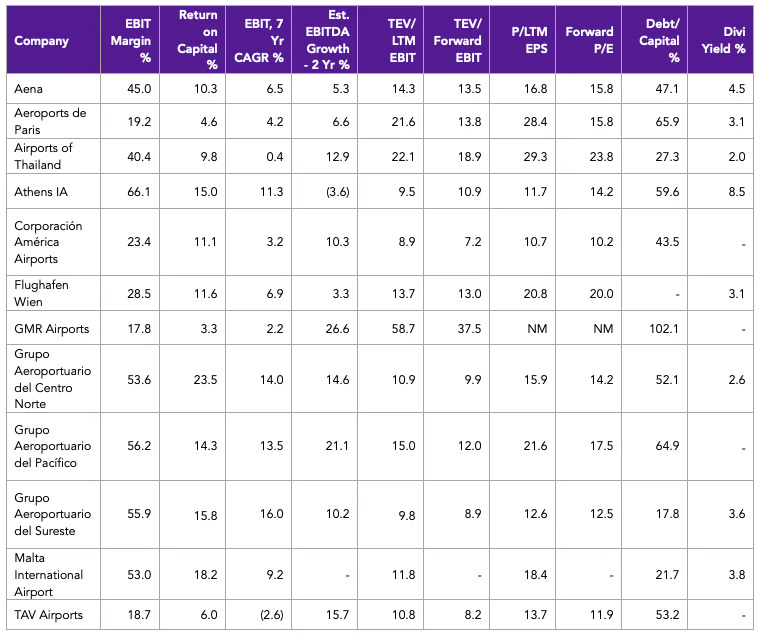
Source: Capital IQ
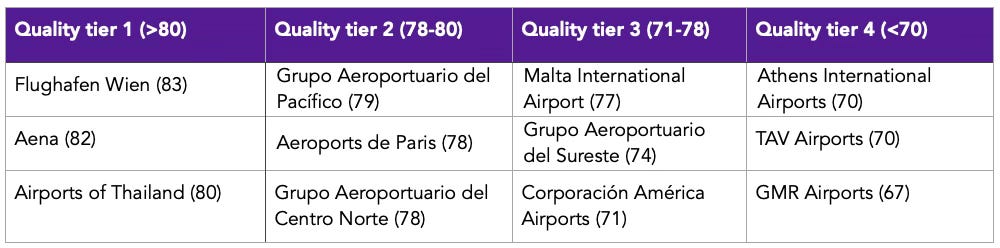
These factors, among others, such as exposure to cyclical tourism markets, market stability, corruption level, currency stability, regulatory transparency and their fundamental qualities such as debt levels, balance sheet strength, profit margins and pricing power, impact the quality score I have for each company, shared on the final column. In the table below, I highlight key financial metrics for each of the twelve companies, and I also split these twelve companies into four quality tiers in another table below.
Source: Jenga IP analysis
Quality tier 1
Flughafen Wien (Austria), Aena (Spain) and Airports of Thailand (Thailand)
Airports like Flughafen Wien, Aena and Airports of Thailand, which own rather than operate as airport concessionaires, maintain domestic dominance, thus significantly raising the barriers to entry, and their value chain control have much higher quality ratings. I view Aena and Flughafen Wien more particularly as the two highest-quality airport groups, and each has attributes that set them apart from its peers.
Flughafen Wien is the only Western listed airport with a debt-free balance sheet, placing them in a unique financial position with virtually no risk of going bankrupt. This has allowed them to deal with external shocks such as the Covid-19 pandemic and financial crisis much better than indebted peers like Aéroports de Paris and take much longer term development investments. Aena, the world's largest airport group, benefits from its exposure to more tourism-led growth markets (Spain and Brazil), which supports its market & positioning, unit economics and profitability (nearly double the profit margins of Flughafen Wien.
Case study - Overpaying for quality
If quality and growth were the sole factors in airport investing, Airports of Thailand (AOT) would be my top airport investment. Thailand's economy is growing much faster than that of its European peers, and its airports have more scope for additional investments in terminals, runways, and overall capacity, supporting a volume-led story. The Suvarnabhumi International Airport in Bangkok recently announced a new terminal and third runway, adding an additional 15 million passengers annually.
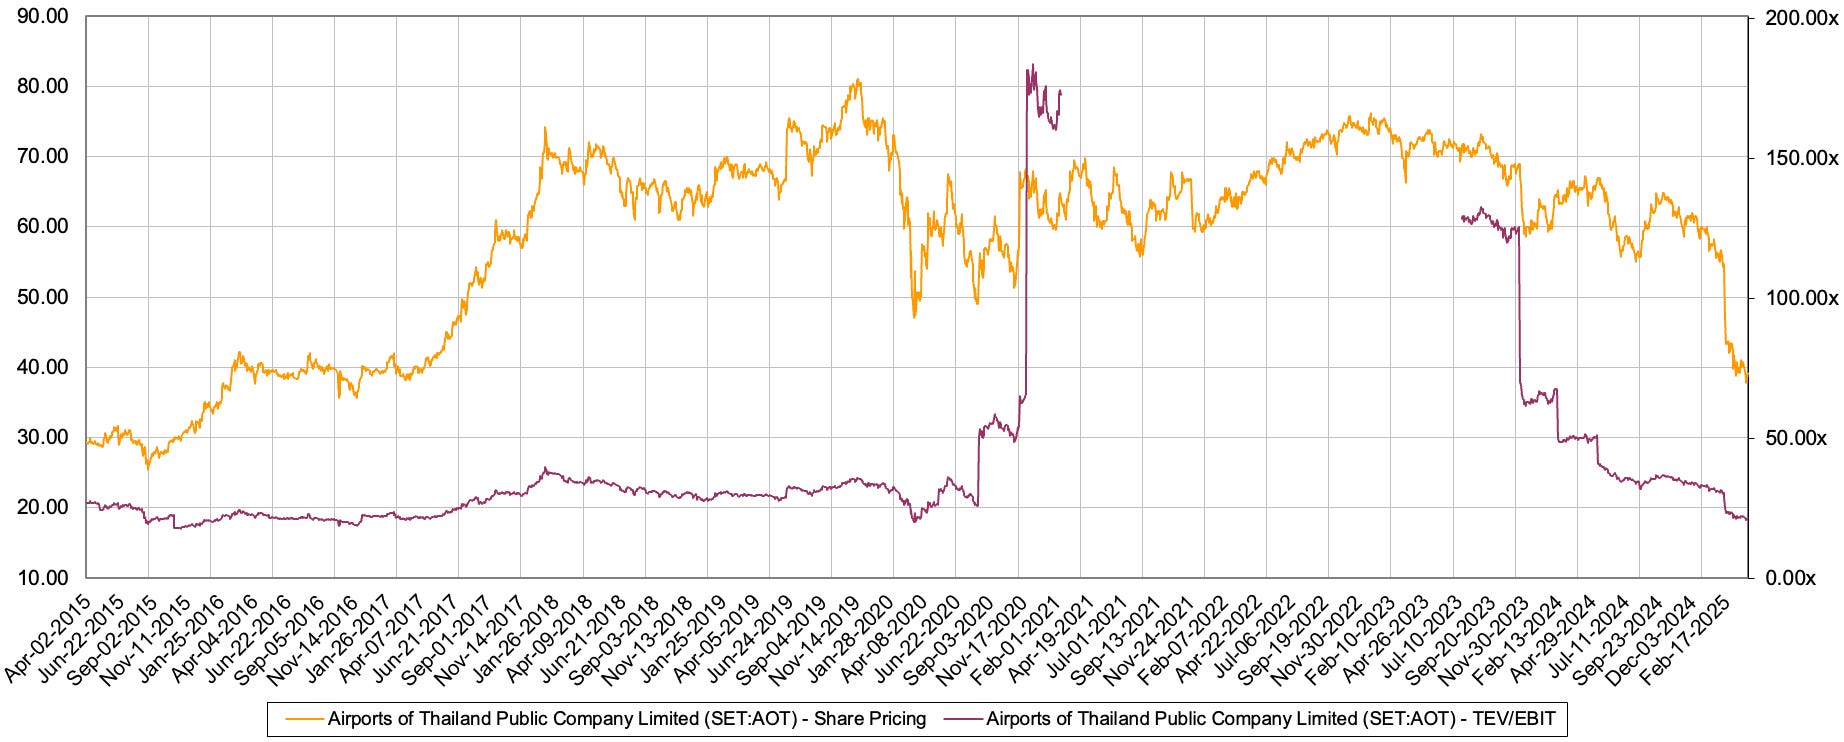
Capital IQ. The slowdown in Chinese tourists during the pandemic greatly impacted Airports of Thailand, causing financial losses in 2020 - 2022.
Despite its quality, Airports of Thailand hasn't necessarily led to a great investment in the past year, a period in which its shares have lost 40% of its value. The simple reason for this underperformance is the valuations markets had paid for its shares. Prior to the pandemic, AOT shares were valued at 42x P/E (33x EV/EBIT), nearly double the limit I will pay for even the highest quality airports. Even the best airports aren't flawless businesses and everything has an appropriate price.
Quality tier 4
Corporación America Airports (Argentina), TAV Airports (Turkey), GMR Airports (India)
Airports tend to reflect their broader economies, and the more volatile an economy is, the more volatile its airport's financials will likely be, which explains why the more volatile countries like Argentina and Turkey host our lower-quality airport companies. Travel in these economies tilts more towards the discretionary end, and the volatility makes it harder for these companies to plan long-term and maintain financial discipline.
To account for these challenges, these airports tend to take on more debt to fund existing operations, e.g. TAV Airports 4.1x debt/EBITDA, GMR Airports 10.1x debt/EBITDA. Given the limited scope for excess capital returns, all three companies also don't pay dividends.
Case study - Airport turnaround opportunities
Given that these airports are closely linked with the fundamentals and sentiment of their domestic countries, their share price and earnings volatility can sometimes create opportunities for turnaround/cyclical investment cases. One company that best portrays this is Corporación América Airports (CAA). Operating earnings from its Argentine airports haven't materially differed in 2018 ($200 mil) versus 2024 ($224 mil), but its share price has rallied nearly four-fold during that period. Its turnaround boils down to two key factors.
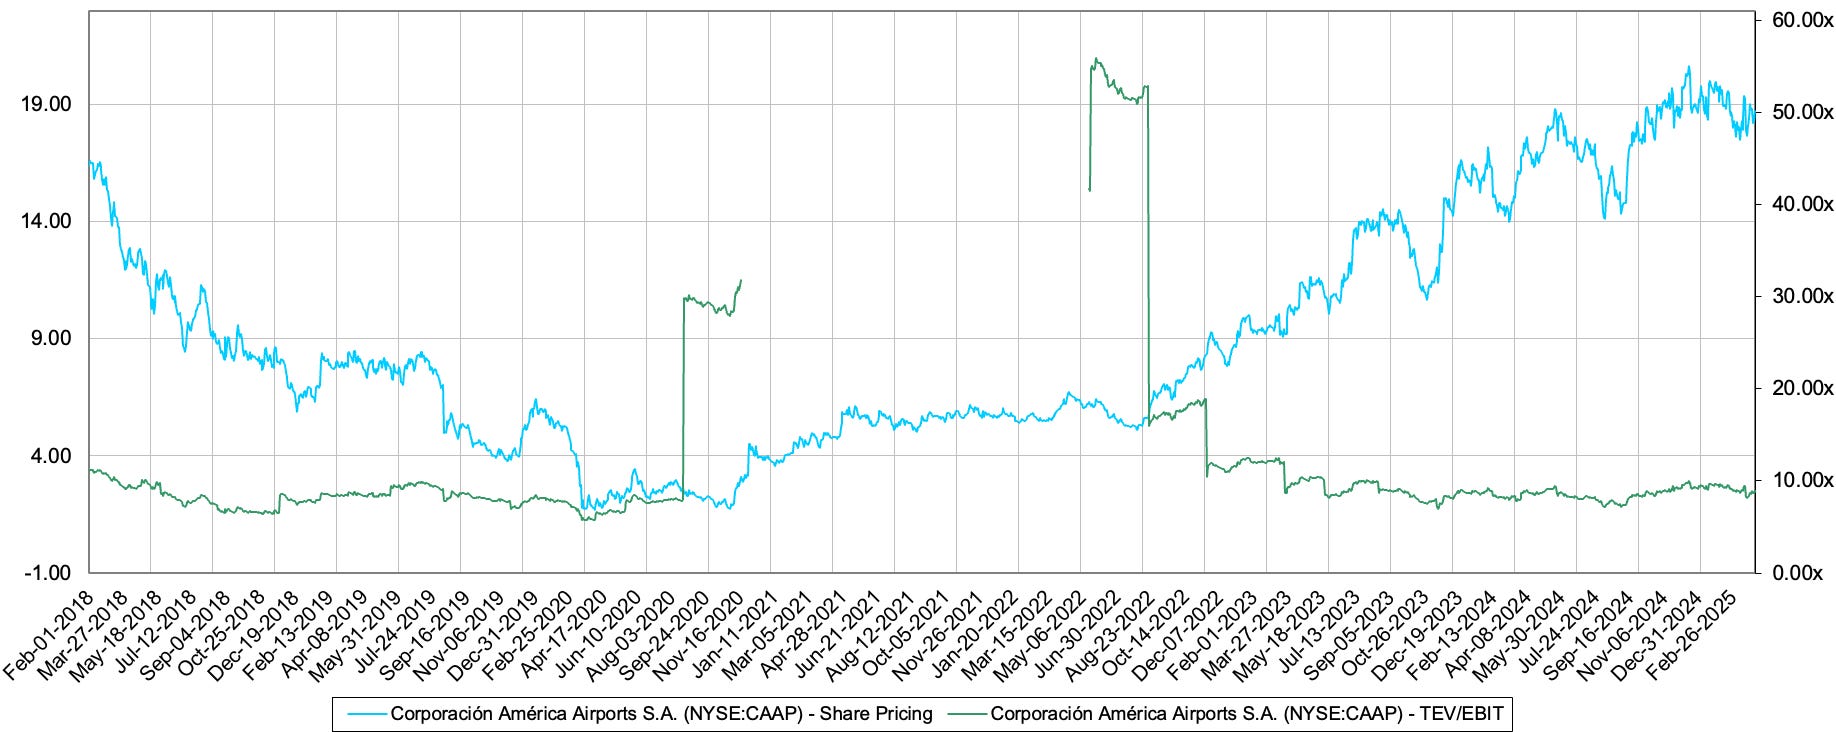
Source: Capital IQ. The sell off in Argentine equities coupled with debt-issues impacted CAA’s share price between 2018-2020.
First, sentiment for Argentine-related stocks took a significant shift in 2021 after years of selling pressures, mainly due to economic challenges such as hyperinflation and government policy. During these periods, investors aggressively sell everything, leading to diversified companies with hidden assets like CAA potentially undervalued, given that their assets are more diversified and have foreign currency exposures from international flights. This hidden foreign currency exposure is a key attribute in many emerging market airport stocks with more reliance on international flights and it's worth calculating these during periods of economic turbulence. Investors who did the legwork and factored in other streams, such as its Armenian airport exposure, were well rewarded for their patience as sentiment and fundamentals turned in 2021.
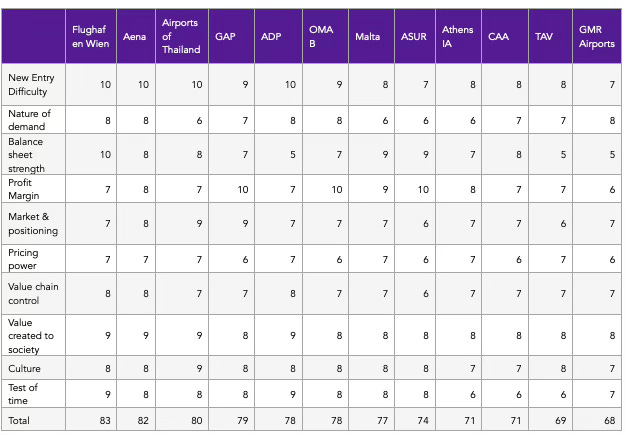
Table: The 12 investable airports on the Jenga IP Quality score
Final thoughts - Airports in the broader infrastructure space
Throughout this report, I have examined airports as investable assets, exploring their evolution through privatisation, the contrasting ownership and concession models, the role of regulation, and an in-depth breakdown of the listed airport landscape.
Profitable and resilient economics: Across the largest 12 listed airport stocks, the average company achieved an EBIT margin of 38% with a return on capital of 11%, well above the average listed company. Airports have also proven to be resilient to most economic shocks and can bounce back from severe challenges like the pandemic.
Predictable economics: Airports are under regulation to follow their long-term Master Development Plans (MDPs), which provides investors with some guidance on long-term earnings potential. Airports also reports some KPIs on a monthly basis, which limits surprises in the short term.
Barriers to entry: Additionally, most listed airports function as legal domestic monopolies, creating formidable barriers to entry. Government ownership, in many cases, extends concession lengths, further boosting their competitive position.
Valuation: At an average multiple of 15.6x earnings, airports currently trade at a discount relative to the global market and with a combination of the above factors, I don’t think this is justified
Challenges in the airport investment theme
Regulatory risks: While regulation poses barriers to entry, it also creates additional risks for current operators, especially those under concessions. A loss of concession or regulatory shift could lead to detrimental impacts on fundamentals.
Limited scope for growth: Airports, by nature, are limited in growth potential. Over the past decade, most have expanded their non-aeronautical revenue, such as food and beverage and duty-free, which has its physical limits.
Cyclical: To some extent, airports can be cyclical businesses, especially those tilted towards tourism markets and those viewed at the more discretionary end. During downturns, these airports are susceptible to losses, which can impact their overall business.
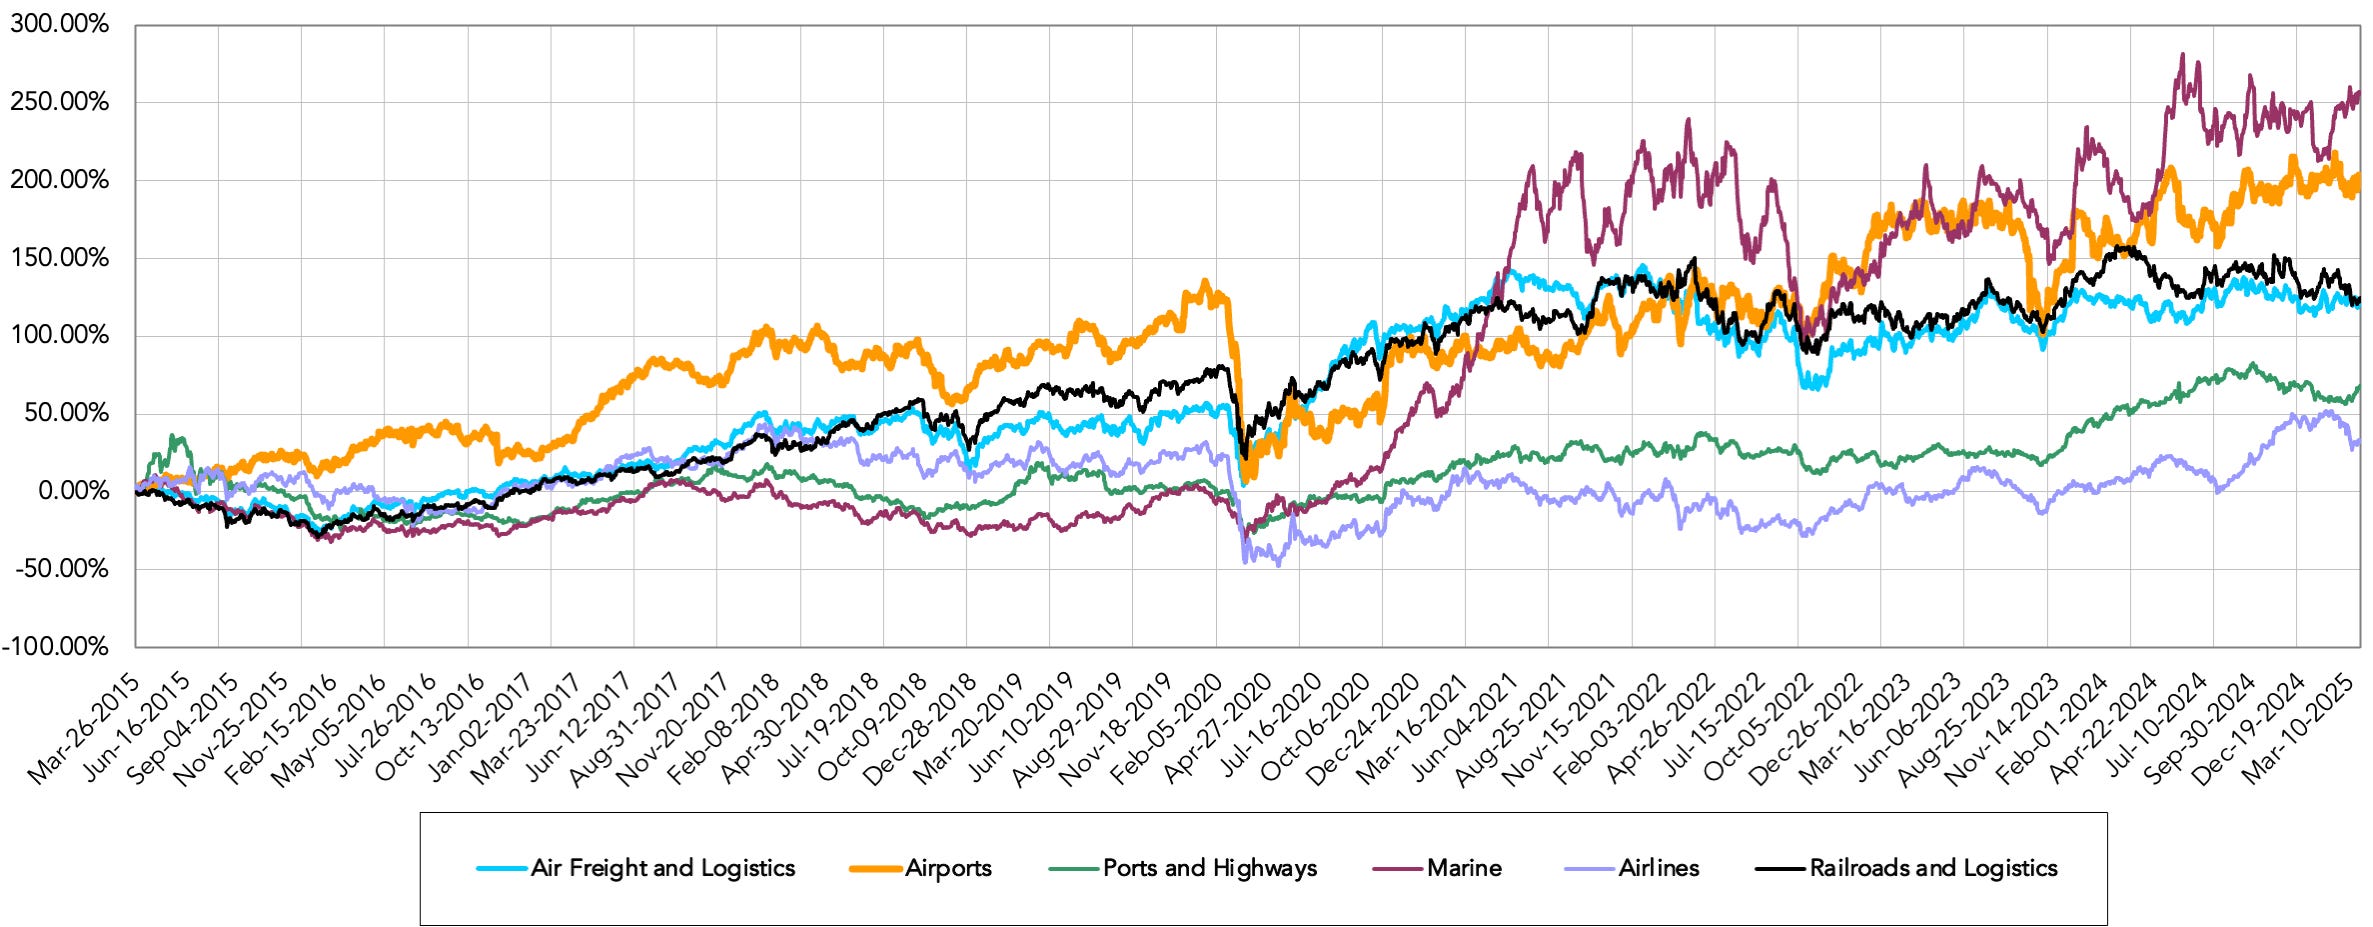
Source: Capital IQ. The dividend adjusted performance of the six transport sub-industries. Airports returned only behind Marine over the ten year period
Given these challenges, assessing how airports compare to other infrastructure assets is helpful to gauge their relative attractiveness.
Source: Capital IQ
Airports vs transport theme
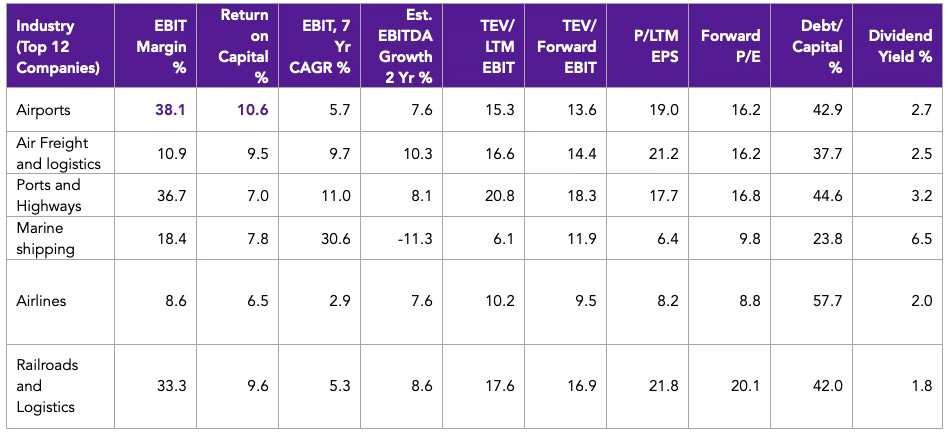
In the table above, I compare the average financials of the twelve largest companies in five key transport sub-industries comparable (railroads and logistics, ports & highways, air freight & logistics, airlines and marine shipping).
While the latter provides a better perspective of the whole transport sector, the former two, railroads & logistics and ports & highways, are much closer from a comparable lens, so it's important to focus on how they perform relative to both.
Profitability: Airports are slightly more profitable than ports & highways and railroads & logistics peers.
Cyclicality: Airports are more resilient than airlines and Marine shipping but less resilient than railroads, ports & highways. When comparing trends of their largest companies, it's clear airports are more exposed to shocks, evidenced by earnings volatility during the pandemic and financial crisis.
Earnings growth: Airports currently underperform on an earnings growth lens, which aligns with our earlier analysis. Both ports & highways and railroads are likely to grow earnings faster over the mid-term, as evidenced by sell-side estimates for their respective largest companies.
Valuations: Among the more earnings-resilient asset classes, airports appear to be the most undervalued on a forward earnings basis. While this discount could reflect concerns over growth limitations, it also suggests potential mispricing relative to their stability and profitability.
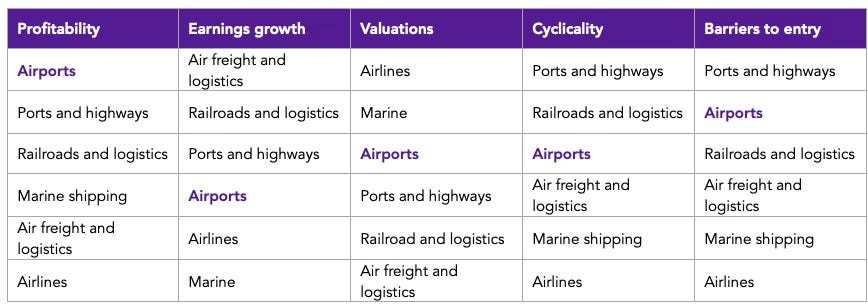
Overall, airports present a compelling investment case due to their profitability, resilience, and structural advantages. However, their exposure to regulatory risks, limited growth opportunities, and economic cyclicality make them less suited for a broad index-style investment approach. Unlike other transport assets, where sector-wide trends can drive long-term gains, airport investing requires a more selective, stock-picking approach. This leads us to the next part, where I analyse two Mexican airport stocks that stand out as particularly attractive opportunities within the space.
I've been listening to quite a bit of Monish Pabrai recently and found his TAV thesis interesting, so thought I'd share his perspective in case it's useful...
He seems to be betting that the market is being overly harsh on TAV's emerging market exposure. A few points that caught my attention:
-Currency protection: 75% of revenues are in EUR/USD or USD-pegged, which might soften the Turkish lira volatility you're rightfully concerned about
-The leverage story: While that 4.1x debt/EBITDA definitely raises eyebrows, Pabrai thinks their 10-14% passenger growth guidance could turn that into a tailwind (potentially 24%+ cash flow growth)
-Geographic spread: 15 airports across 8 countries rather than pure Turkey risk
-Valuation: He keeps emphasising they're "very cheap vs other global airport operators"
The Almaty acquisition seems to be his proof point - $120M equity investment already generating $116M EBITDA with more growth expected.
Obviously your quality framework makes total sense, especially around financial stability. I'm curious what you think about his thesis - is there something he might be missing about the structural challenges, or could this be one of those rare times where the market's EM pessimism creates opportunity?
Problem with airport is you are always going to be beholden to the government as a partner, who has the potential to be irrational and skew incentives. I'd be more interested if you could ever have a 'for profit' 100% publicly owned airport. But how these companies are currently constructed it makes them natural to be placed with big private investors who have the scale and deep pockets to deal with the local governments. As a small public investor, you are stuck hanging in the wind so to speak.